MORTGAGE REFINANCING

MORTGAGE REFINANCING

Six reasons to refinance. A few reasons not to.

Six reasons to refinance. A few reasons not to.

Six reasons to refinance. A few reasons not to.

The homeowners who get the most out of refinancing are solving a specific problem. Lower payments. Access to equity. Dropping mortgage insurance. Paying off the home sooner. Getting off an adjustable rate. Taking a name off the loan. Each goal points to a different kind of refinance, and some point away from refinancing altogether.

This guide will help you think through whether refinancing is the right tool for the job.

Start with the reason, not the rate.

A refinance replaces your existing mortgage with a new loan. The new loan pays off the old one, and you begin making payments under new terms.

That new loan can change your rate, payment, loan length, monthly cash flow, equity access, and long-term interest cost. It also resets the amortization clock, which is one of the details homeowners often underestimate.

"Can I get a lower rate?" is the wrong first question.

The right one: What am I trying to change, and is a refinance the cheapest way to change it?

WHY CONSIDER REFINANCING

WHY CONSIDER REFINANCING

Six goals. Six different refinance conversations.

Six goals. Six different refinance conversations.

Most refinances begin with one of these goals. Choose the one closest to your situation, then use the calculator below to test whether the numbers support the strategy.

CASH FLOW

Lower your monthly payment.

Reduce monthly pressure by lowering your rate, lengthening your term, or both.

Improving monthly cash flow is the most common refinance goal. A lower payment can free up money for savings, investments, home improvements, or other priorities.

The important question is whether the monthly savings are large enough to justify the closing costs and any added time on the loan. A lower required payment can be useful. Stretching out a balance you were close to paying down can be costly.

The break-even calculator below helps test that trade-off.

PAYOFF SPEED

Pay off the home sooner.

Move from a 30-year loan into a 20-, 15-, or 10-year structure.

Some homeowners refinance into a shorter term to build equity faster and reduce total interest paid. Monthly payments may rise, but the long-term savings can be significant.

This often makes sense when income has grown since the original purchase, when retirement planning becomes more important, or when the current mortgage timeline no longer fits the homeowner’s goals.

HOME EQUITY

Access built-up equity.

Convert part of your home equity into cash for a specific purpose.

A cash-out refinance lets you replace your current mortgage with a larger new loan and receive part of the difference in cash.

Homeowners may use this for renovations, debt consolidation, education costs, or major expenses. Used strategically, it can be a useful financial tool. Used casually, it can turn short-term spending into long-term debt.

If your current first mortgage has a rate you do not want to lose, a home equity loan or HELOC may be a better fit than refinancing the entire mortgage.

MORTGAGE INSURANCE

Drop mortgage insurance.

If your equity has passed 20%, you may be able to remove PMI.

If your home value has increased or your loan balance has dropped, you may have enough equity to remove private mortgage insurance.

Refinancing can sometimes eliminate PMI, but it is not always the first move. Many servicers will remove PMI without a refinance once you document that your loan-to-value ratio meets their requirements, sometimes with a new appraisal.

Before assuming you need to refinance, ask your current servicer what PMI removal options are available.

RATE STABILITY

Move off an adjustable rate.

Trade ARM uncertainty for the predictability of a fixed-rate mortgage.

If you have an adjustable-rate mortgage, refinancing into a fixed-rate loan can protect you from future payment changes and make monthly planning easier.

The right timing depends on how close you are to your next adjustment, what your current ARM terms allow, and how fixed-rate options compare to your projected future payment.

This is a conversation worth having before the reset window gets close.

BORROWER CHANGE

Change who is on the loan.

Refinancing can remove or add a borrower after a major life change.

Refinancing can be the cleanest way to remove a co-borrower after a divorce, buyout, estate change, or ownership transition.

Because the new loan pays off the old one, the financing can be restructured under the borrower or borrowers who will remain responsible for the mortgage.

This type of refinance is less about rate shopping and more about creating a clean financial structure.

CASH FLOW

Lower your monthly payment.

Reduce monthly pressure by lowering your rate, lengthening your term, or both.

Improving monthly cash flow is the most common refinance goal. A lower payment can free up money for savings, investments, home improvements, or other priorities.

The important question is whether the monthly savings are large enough to justify the closing costs and any added time on the loan. A lower required payment can be useful. Stretching out a balance you were close to paying down can be costly.

The break-even calculator below helps test that trade-off.

PAYOFF SPEED

Pay off the home sooner.

Move from a 30-year loan into a 20-, 15-, or 10-year structure.

Refinancing into a shorter loan term can reduce the number of years you remain in debt and may substantially lower the total interest paid over the life of the loan.

The trade-off is usually a higher required monthly payment. Compare the new payment, closing costs, interest rate, and projected payoff date before deciding whether the shorter term improves your overall position.

HOME EQUITY

Access built-up equity.

Convert part of your home equity into cash for a specific purpose.

A cash-out refinance lets you replace your current mortgage with a larger new loan and receive part of the difference in cash.

Homeowners may use this for renovations, debt consolidation, education costs, or major expenses. Used strategically, it can be a useful financial tool. Used casually, it can turn short-term spending into long-term debt.

If your current first mortgage has a rate you do not want to lose, a home equity loan or HELOC may be a better fit than refinancing the entire mortgage.

MORTGAGE INSURANCE

Remove private mortgage insurance.

If you have a conventional loan and sufficient equity, you may be eligible to remove PMI.

As your loan balance decreases or your home value increases, you may reach the equity level required to cancel private mortgage insurance.

Refinancing can sometimes eliminate PMI, but it is not always the best first step. Depending on your loan, you may be able to request removal through your current servicer without refinancing. Eligibility can depend on your loan balance, payment history, property value, and servicer or investor requirements.

Before assuming you need to refinance, ask your current servicer what PMI removal options are available.

RATE STABILITY

Move off an adjustable rate.

Trade ARM uncertainty for the predictability of a fixed-rate mortgage.

If you have an adjustable-rate mortgage, refinancing into a fixed-rate loan can protect you from future payment changes and make monthly planning easier.

The right timing depends on how close you are to your next adjustment, what your current ARM terms allow, and how fixed-rate options compare to your projected future payment.

This is a conversation worth having before the reset window gets close.

BORROWER CHANGE

Change who is on the loan.

Refinancing may allow a borrower to be added or removed after a major life or ownership change, subject to credit, income, title, and program requirements.

Refinancing can be the cleanest way to remove a co-borrower after a divorce, a buyout, an estate change, or an ownership transition. Because the new loan pays off the old one, it can be structured around the person or people who will actually carry the mortgage going forward. Here the rate is secondary; the point is getting the loan into the right names.

RUN THE NUMBERS

The break-even point is the math that matters.

Every refinance has costs. Every refinance should create a measurable benefit. The break-even point tells you how many months it takes for the monthly savings to repay what the refinance costs.

If your break-even point is 24 months and you plan to keep the home for ten more years, the refinance may be worth a closer look. If your break-even point is 72 months and you may sell in three years, the lower rate may not matter.

Use the calculator below to test the basic math.

Refinance Estimator
Estimate how refinancing could affect your monthly payment.
Current Loan Details
Current Loan Amount
$
Current Interest Rate
%
Duration of Current Loan
Origination Year
New Loan Details
New Loan Amount
$
New Interest Rate
%
Cash Out Amount
$
Estimated Closing Costs
%
Duration of New Loan
Calculator results

This calculator estimates your potential monthly savings from refinancing your current mortgage into a new loan. Enter your current loan details, including the remaining balance, interest rate, and original loan term, along with the terms of the new loan you're considering. If you plan to take cash out, include that amount as well.

Use the results to compare your current and new monthly payments, estimate long-term savings, and get a rough sense of how quickly a refinance might pay for itself. This tool is for planning purposes, not a final quote.

Refinance savings depend on factors this calculator can't fully account for. Your credit profile, the loan program you qualify for, current market rates, and closing costs all play a role.

We're happy to run the real numbers for you, compare loan options side by side, and help you decide if refinancing makes sense right now. There's no obligation, and it only takes a few minutes.

Your monthly savings from refinancing depend on several variables:

  • •Interest Rate Difference - Even a small rate reduction can meaningfully lower your payment over time
  • •Remaining Loan Balance - A higher balance amplifies both savings and costs
  • •New Loan Term - A shorter term builds equity faster but may increase your monthly payment
  • •Cash-Out Amount - Taking cash out increases your new loan balance and affects your savings
  • •Closing Costs - Typically 2–5% of the loan amount; your break-even timeline accounts for these
  • •Time Remaining on Current Loan - The more time left, the more interest you could potentially save, making earlier refinances more viable than later ones

A common rule of thumb is that refinancing makes sense when you can reduce your rate by at least 0.5–1%, plan to stay in the home long enough to recoup closing costs, and the new loan term aligns with your financial goals. That said, every situation is different. Market rates, your current equity position, and your plans for the home all factor in. A Thompson Kane loan officer can help you evaluate whether the timing is right for you specifically.

Provide a start date in the mortgage payment calculator to see the loan's amortization details.

Disclaimer ~ How to Read the Results

The figures generated by this calculator are for informational and planning purposes only. They do not represent a loan offer, pre-approval, commitment to lend, or guarantee of specific loan terms, costs, or savings. Actual refinance results, including your interest rate, monthly payment, closing costs, break-even timeline, and total interest paid, will depend on your credit history, income, assets, debt obligations, property type and value, loan program, and prevailing market conditions at the time of application.

The break-even estimate uses the closing-cost percentage you enter in the calculator. The 2.5% shown in that field is a suggested starting point, not a pre-filled value: if you leave the field blank, your estimate will not include any closing costs at all. Actual closing costs typically range from 2–5% of the loan amount and vary based on lender fees, third-party services, prepaid items, and location. Your loan officer can tell you what to expect for your specific loan. Mortgage insurance, property taxes, and homeowners insurance are not reflected in these estimates and may affect your total monthly housing cost.

Thompson Kane & Company is a licensed direct mortgage banker. All loans are subject to credit approval and standard underwriting guidelines. Rates, programs, and terms are subject to change without notice and may not be available in all areas.

For a personalized refinance analysis based on your actual loan profile, connect with a Thompson Kane loan officer.

Frequently asked questions

Accurate enough to tell you whether refinancing is worth a closer look, but it's still an estimate. Your actual savings will depend on the rate you qualify for, your remaining loan balance, your credit profile, and the closing costs specific to your situation. Use it to test the math, then talk to a Thompson Kane loan officer to find out what's actually on the table for you.

The old rule of thumb, "Only refinance if you can drop your rate by 1% or more", is too blunt to be useful. What actually matters is your break-even point: how long it takes for your monthly savings to recover the cost of refinancing. If you plan to stay in the home past that point, refinancing likely makes sense. If you're moving in two years, it probably doesn't, even at a meaningfully lower rate.

Your break-even point is the month when your cumulative monthly savings finally exceed what the refinance cost you at closing. Before that point, you're still in the red. After it, every month is money back in your pocket. It's the single most important number in the decision, and it should drive both whether you refinance and when.

Refinancing isn't free. Closing costs typically run between 2% and 5% of the loan amount. Those costs can be paid upfront, rolled into the new loan, or sometimes offset through a slightly higher rate. Each approach has tradeoffs. Rolling costs into the loan keeps cash in your pocket today but increases what you owe. A Thompson Kane loan officer can lay out the options side by side so you can see what each one actually costs you over time.

It can. That's worth paying attention to. If you've been paying on a 30-year mortgage for seven years and you refinance into a new 30-year loan, you're resetting the clock. Your payment may go down, but your payoff date moves out and your total interest paid could actually increase. Refinancing into a shorter term, say, from a 30-year into a 15-year, avoids that problem and often comes with a lower rate, though your monthly payment will be higher.

A rate-and-term refinance replaces your existing loan with a new one at a better rate, a different term, or both. The goal is a lower payment or faster payoff. A cash-out refinance lets you borrow against your home equity, replacing your mortgage with a larger loan and taking the difference in cash. Both are legitimate tools, but they serve different goals. If you're carrying high-interest debt or facing a large expense, cash-out can make sense, but it increases what you owe on your home, so it deserves careful thought.

Significantly. Even a 20- or 30-point difference in credit score can move your rate enough to change whether refinancing makes financial sense. If your score has improved since you took out your original loan, that alone can be a compelling reason to explore a refinance. If it's dropped, it may be worth waiting or taking steps to improve it before applying.

COMMON PITFALLS

Two refinance mistakes are easy to miss.

A refinance can look attractive at first glance and still be the wrong move. Before you focus on the rate alone, watch for these two common mistakes.

Mistake 1: Focusing only on the interest rate

A lower rate helps, but it is not the whole decision. Closing costs, loan term, monthly savings, how long you plan to stay in the home, and the total interest picture all matter.

A refinance with a modest rate improvement can still make sense if it solves the right problem. A refinance with a dramatic rate improvement can still be questionable if the cost takes too long to recover.

Mistake 2: Ignoring the amortization clock

When you refinance, the loan starts over under new terms. If you replace a mortgage you have already paid for seven years with a fresh 30-year loan, you may reduce your monthly payment while adding years of payments back onto the end.

That may be acceptable if cash flow is the main goal. But it should be a conscious trade-off, not a surprise.

Mistake 1: Focusing only on the interest rate.

A lower rate helps, but it is not the whole decision. Closing costs, loan term, monthly savings, how long you plan to stay in the home, and the total interest picture all matter.

A refinance with a modest rate improvement can still make sense if it solves the right problem. A refinance with a dramatic rate improvement can still be questionable if the cost takes too long to recover.


Mistake 2: Ignoring the amortization clock

When you refinance, the loan starts over under new terms. If you replace a mortgage you have already paid for seven years with a fresh 30-year loan, you may reduce your monthly payment while adding years of payments back onto the end.

That may be acceptable if cash flow is the main goal. But it should be a conscious trade-off, not a surprise.

WATCH THE AMORTIZATION CLOCK

A lower payment can still cost more over time.

One of the most overlooked refinance details is the way a new loan resets the repayment timeline.

For example, if you are five years into a 30-year mortgage and refinance into a new 30-year mortgage, you have not simply improved your old loan. You have restarted the clock, adding five more years of mortgage payments.

Two ways to avoid that trap:

  • Refinance into a shorter term, such as a 20-year loan instead of a new 30-year loan.

  • Keep paying your old monthly amount even though the new required payment is lower. The new payment becomes the minimum; the extra goes straight to principal. With a lower rate working underneath, you can come out ahead of your original payoff date.

The right structure depends on your goal. What matters is seeing the trade-off before you sign.

Five years into a 30-year mortgage, this borrower refinanced into a new 30-year loan. Total time carrying a mortgage: 35 years. Whether that trade makes sense depends on whether the new rate saves more than the added years cost.

GOVERNMENT-BACKED LOANS

If your loan is FHA, VA, or USDA, you may have a faster path.

If your current mortgage is FHA, VA, or USDA, you may qualify for a streamlined refinance with reduced documentation, lighter underwriting, and fewer steps than a standard refinance.

FHA Streamline

For eligible borrowers with an existing FHA-insured loan. Typically involves limited documentation and may be completed without a new appraisal.

VA IRRRL

The VA Interest Rate Reduction Refinance Loan is for eligible current VA loans and is designed to make qualifying rate reductions faster and more efficient.

USDA Streamlined Refinance

For current USDA loans. May allow limited documentation and no new appraisal in many cases.

Each program has its own requirements around timing, payment history, and borrower benefit. When a streamline option applies, it can be one of the cleanest refinance paths available.

EXCEPTIONS

Sometimes the right move is to keep the mortgage you already have.

Refinancing is not automatically beneficial. A lower rate or lower payment can still come with trade-offs that do not fit your situation.

A refinance may not make sense if:

  • You expect to move before the break-even point.

  • The monthly savings are too small to justify the closing costs.

  • Extending the loan term would significantly increase your total interest.

  • You are solving a short-term cash issue with long-term mortgage debt.

  • You can accomplish the same goal more efficiently another way.

  • Your current first mortgage rate is unusually favorable.

Knowing when not to refinance is part of doing it well.

"A refinance should solve a real problem, not just create a new loan."

— John Thompson, CEO & Founder

UNDERSTANDING REFINANCING COSTS

What does a refinance cost?

Like a purchase mortgage, a refinance usually includes closing costs. These may include lender fees, appraisal costs, title services, recording fees, escrow items, and prepaid expenses.

Depending on the loan, those costs may be:

  • Paid up front

  • Rolled into the new loan balance

  • Offset with a lender credit in exchange for a different rate structure

A “no closing cost” refinance is not free. The cost is usually built into the rate, loan balance, or overall structure. That does not mean it is bad. Sometimes it is the right fit. But it should be compared honestly.

That is why the break-even math matters.

WHAT TO ASK YOURSELF

Five questions to ask before you refinance.

Before you move forward, ask:
  1. What am I trying to accomplish?

  1. How long do I expect to keep this home or loan?

  1. What is my break-even point?

  1. How does this change my total interest paid?

  1. Is there a less expensive way to accomplish the same goal?

Honest answers to these questions often clarify the decision before a rate quote is even involved.

HOW WE HELP

A loan officer runs this comparison with you.

Sometimes the numbers support a refinance. Sometimes a HELOC, a PMI removal request, or simply keeping your current mortgage makes more sense.

A Thompson Kane loan officer can help you compare:

  • Your current mortgage

  • Your current equity position

  • Available refinance options

  • Estimated closing costs

  • Monthly savings

  • Break-even timeline

  • Long-term interest impact

  • Cash-out, HELOC, or home equity alternatives

If refinancing makes sense, we will help you find the structure that fits the goal. If your current loan is the one to keep, we will tell you that too.
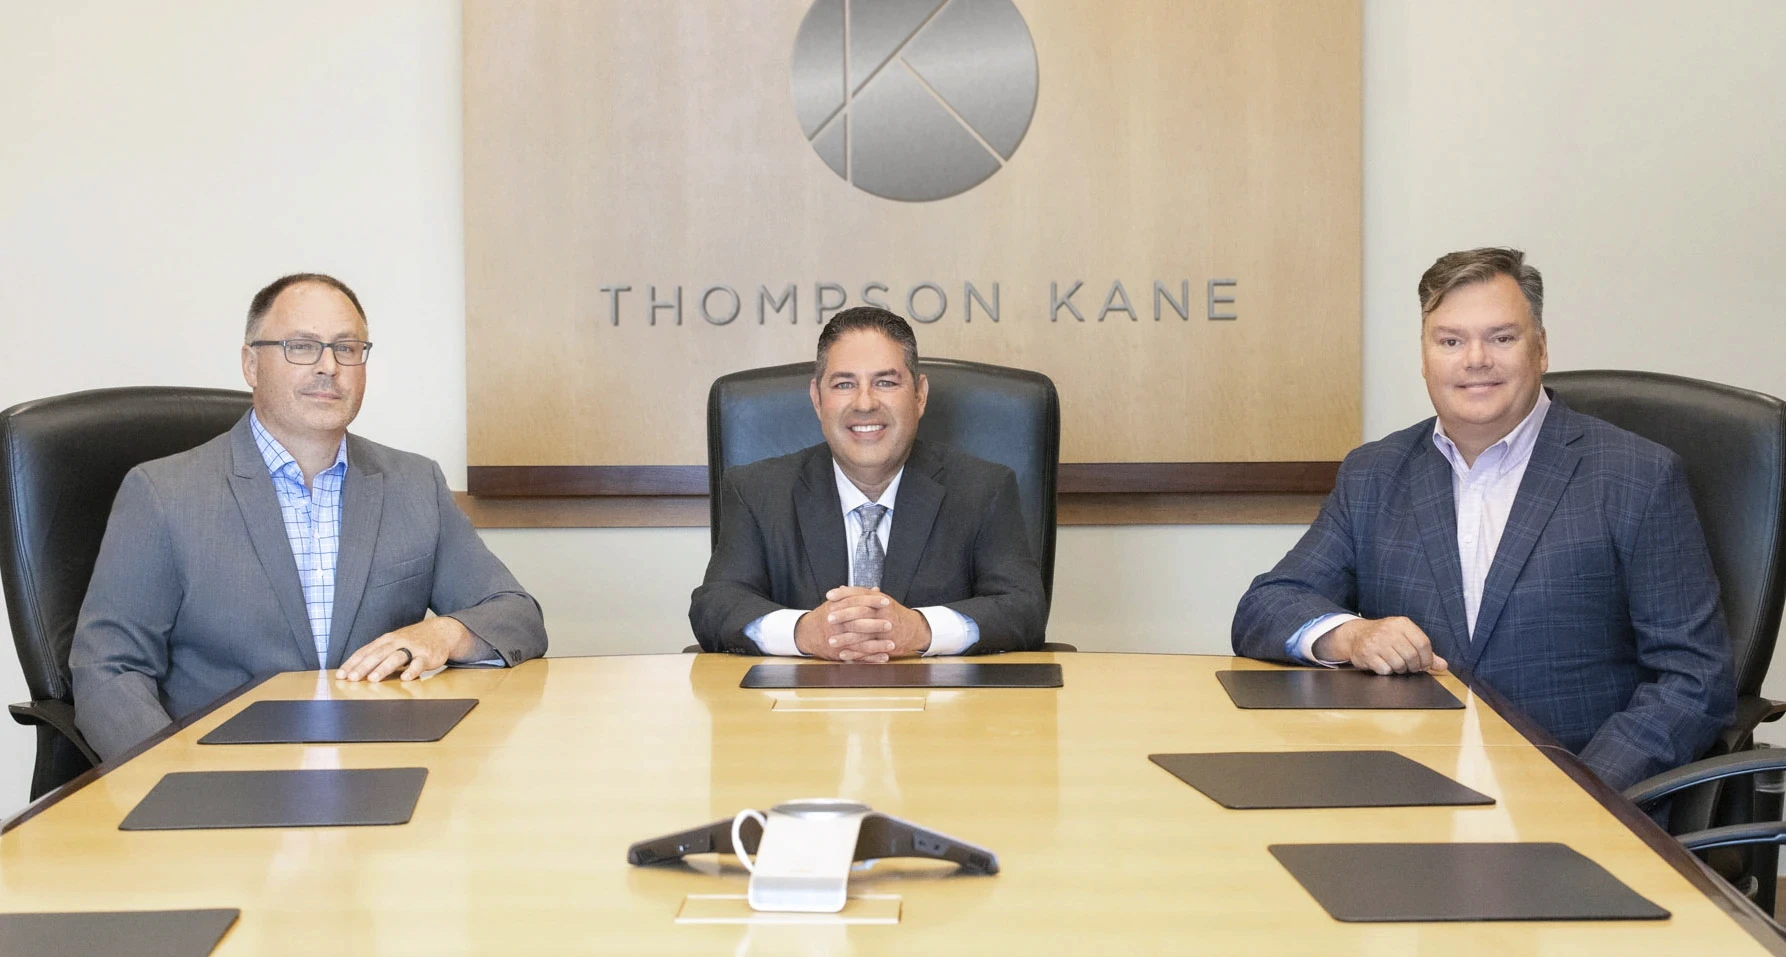
Thompson Kane's senior leadership team, from left, Patrick Averill, Wes Kane, and John Thompson.

Thompson Kane's senior leadership team, from left, Patrick Averill, Wes Kane, and John Thompson.

Let's look at your options together.

One of the six goals above may fit your situation. Or you may simply want to know whether current loan options are worth considering. Maybe you're just wondering whether the market has handed you a reason to look. Either way, the next step is the same: a loan officer reviews your current mortgage, runs the numbers on your actual loan, and walks you through the comparison.